How to Secure Funding for a Small Business
To secure funding for a small business, work out exactly how much you need and what it pays for, choose the type of funding that fits your business, and prepare the documents lenders and investors ask for: a business plan, a financial forecast and a clear use of funds. Then pitch it, and track the money once it arrives. Most refusals come from a vague amount or numbers that don’t add up, not from the idea itself.
Funding to raise = startup or growth budget − cash you put in yourself, rounded up to an amount you can explain line by line
Key takeaways
- Start with the amount. Lenders and investors ask “how much, and for what?” before anything else.
- Loans cost interest but keep you in control. Investors take a share of the business but share the risk.
- A use-of-funds table and a 3-year forecast do more for your application than a long pitch.
Step 1: Check that you need outside funding
Outside money is worth it when it pays for something that brings in more cash than it costs. Answer three questions before you ask anyone:
- What will the money pay for? Name the items: stock, equipment, a fit-out, hiring.
- When will it pay back? Your forecast should show the month your cash flow can carry repayments or justify an investor’s share.
- What happens without it? If you can start smaller and grow from sales, that may be cheaper than a loan or giving away equity.
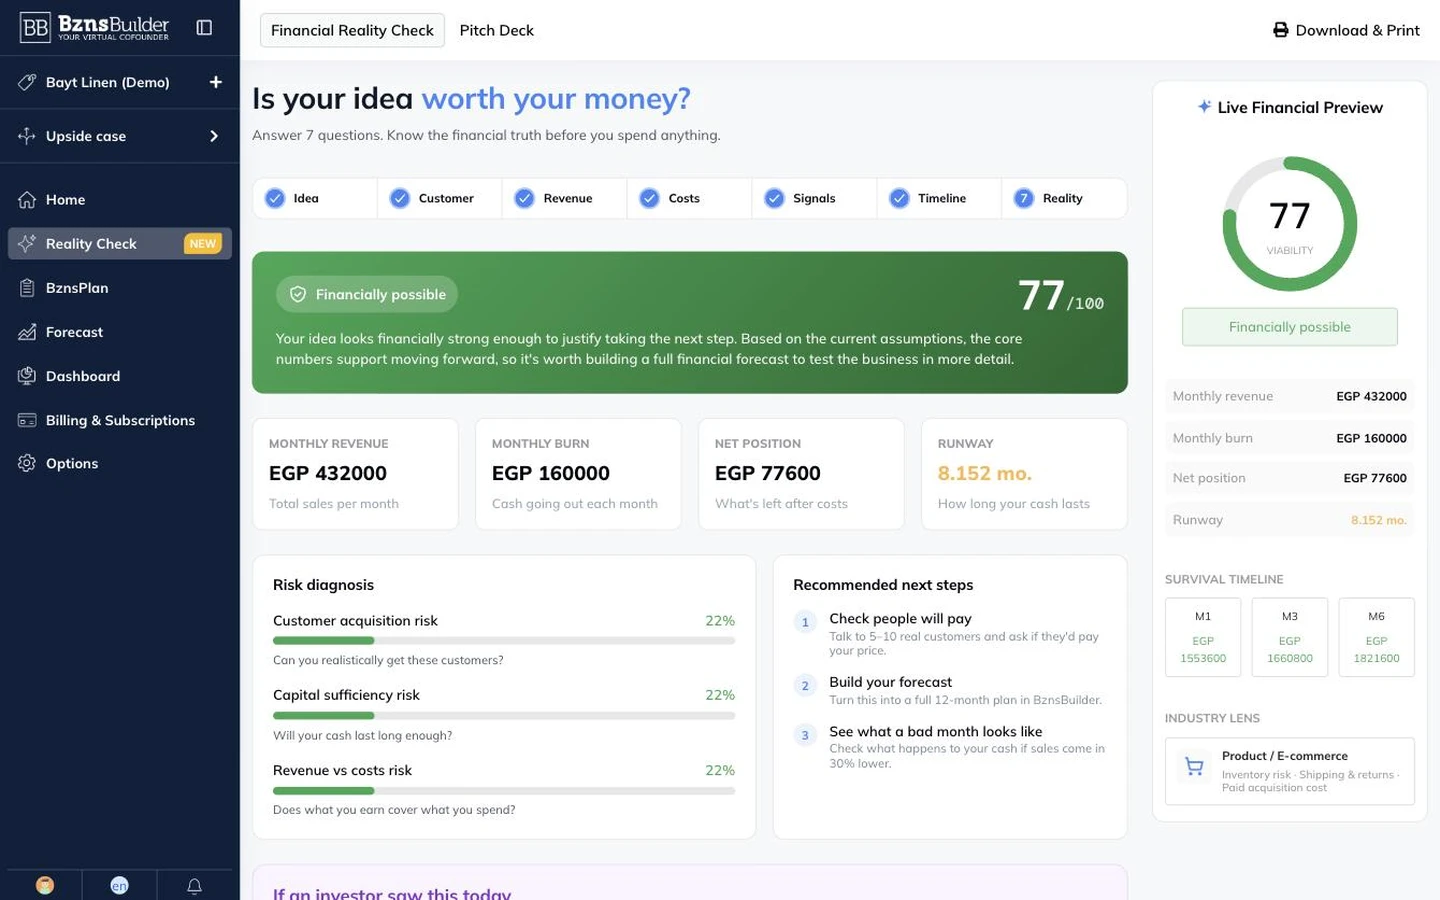
Not sure the idea is strong enough to borrow against? Run a Reality Check. It rates six signals against your industry, including cash runway and financial readiness, and gives a viability score out of 100 before you ask anyone for money.
Step 2: Work out how much to raise
Start from your startup or growth budget, subtract what you can put in yourself, and round the gap up to a figure you can explain line by line. Asking for too little is as risky as asking for too much: you run out of cash before the plan works.
Example: the small online store from our startup costs guide needs a startup budget of $10,010. The founder has $4,000 in savings. That covers registration, the first month’s fixed costs and the four-month cash buffer, with $400 left for surprises. The gap is $6,010, so the founder asks for $6,200 and shows exactly where it goes:
| Use of funds | Amount | When |
|---|---|---|
| Opening stock | $3,000 | Month 0 |
| Website and product photos | $800 | Month 0 |
| Equipment | $700 | Month 0 |
| Branding and launch | $600 | Months 0–1 |
| Storage deposit | $400 | Month 0 |
| Cash reserve | $700 | Held back |
| Total requested | $6,200 |
Test the cost of the money, too. Rates and fees differ between lenders and change over time, so ask each one for the full yearly cost and put it in your forecast. On a $6,200 loan repaid over two years, the monthly repayment is about $304 at 16% a year and about $328 at 24%.
Free template: use-of-funds table + funding checklist (Excel)
Enter your budget, your own cash and the amount you ask for; the sheet works out the gap and each line’s share, and checks the lines add up. The second tab is a 15-item checklist of what lenders and investors ask for, with a progress score.
Not sure of your budget yet? Use the startup cost calculator first.
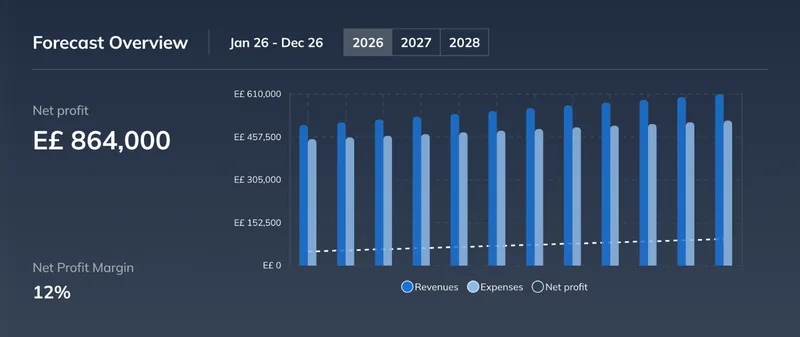
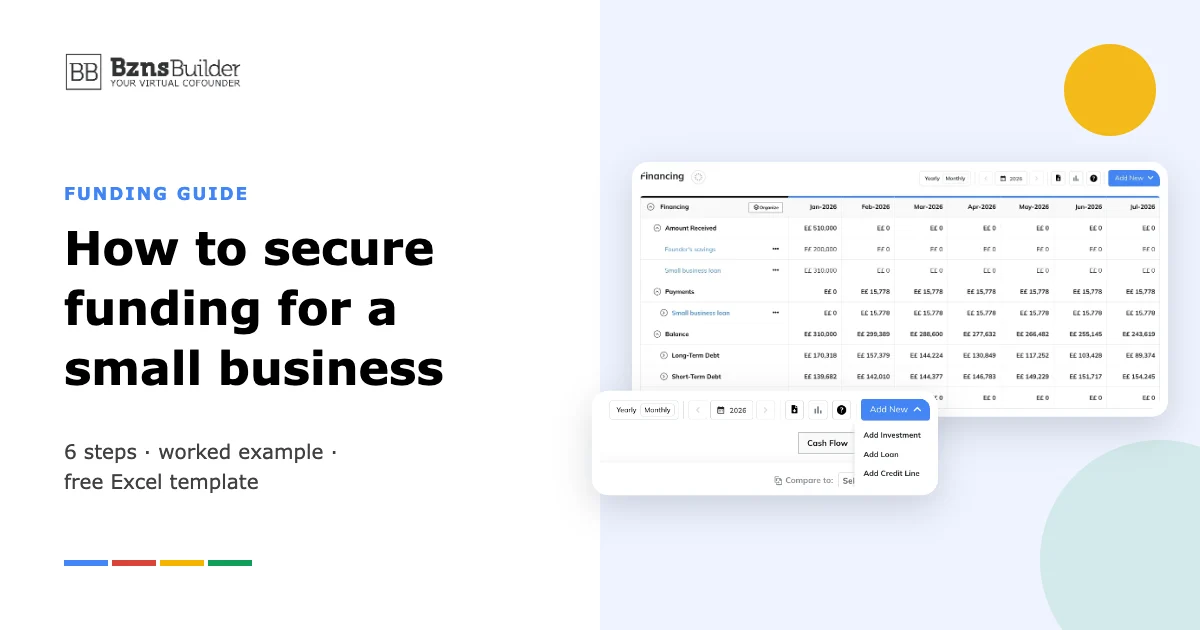
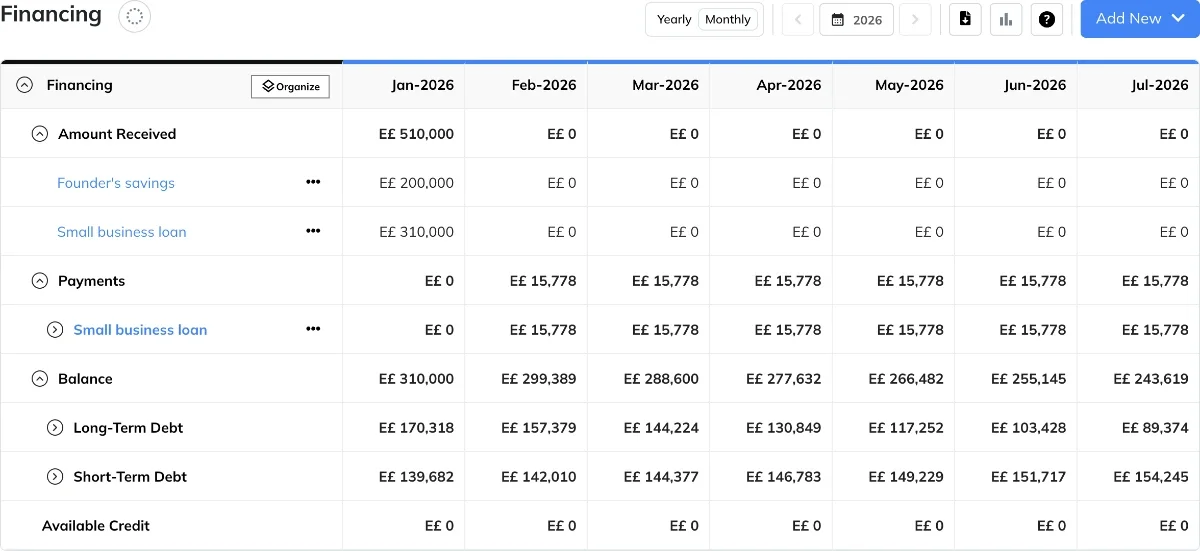
The amount you ask for should come out of a forecast, not a guess. BznsBuilder’s financial forecast builds your profit and loss, balance sheet and cash flow month by month for up to 10 years. Add the loan or investment under Financing and the repayments flow through all three statements, so you see the month cash gets tight before you sign. Forecast suggestions help with the numbers you’re unsure about, and on the Build plan the automatic forecast builder and AI-powered forecasting give you a first draft to edit.
Step 3: Choose the type of funding
Funding comes in two main forms. Debt (a loan or credit line) is repaid with interest, and you keep full ownership. Equity (angel or venture investment) gives an investor a share of the business in return for money and, often, advice. Most small businesses combine their own savings with one or two of these:
| Option | What you give up | Speed | Usually suits |
|---|---|---|---|
| Your own savings | Personal risk | Immediate | Every founder, for at least part of the budget |
| Family and friends | Relationships if it goes wrong; put terms in writing | Fast | Early, small amounts |
| Bank loan or credit line | Interest; often collateral or a guarantor | Weeks | Businesses with steady cash flow or assets |
| Government-backed programmes | Paperwork; eligibility rules | Weeks to months | Small businesses that meet the programme’s criteria |
| Supplier credit | Less room to negotiate on price | Fast | Retail and trading, to fund stock |
| Angel or venture investors | A share of ownership and some control | Months | Fast-growing businesses that can scale |
| Grants and competitions | Time to apply; reporting | Months | Specific sectors, early-stage or social ventures |
| Crowdfunding | Public campaign effort; delivery promises | 1–2 months | Consumer products with a clear audience |
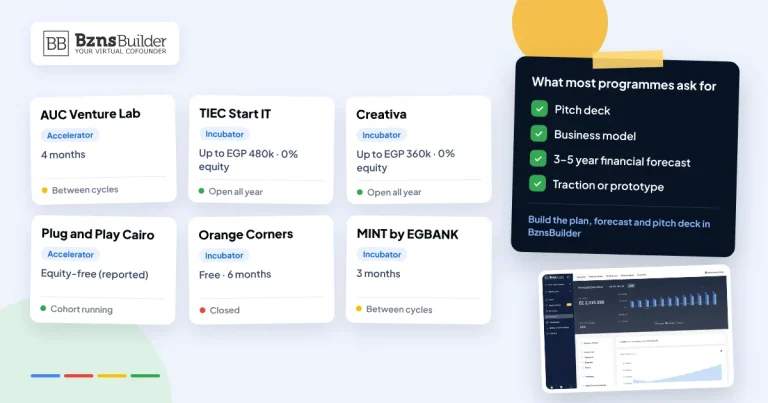
In Egypt, several incubators and accelerators offer funding or support without taking equity. See startup incubators and accelerators in Egypt.
Debt or equity: which fits you?
Choose debt if your business already has, or will soon have, steady cash flow that can cover repayments, and you want to keep full ownership. Choose equity if the business needs a large amount before it earns, the risk is high, or you want an investor’s network and experience. Many founders start with savings and a small loan, and raise equity only when growth needs it.
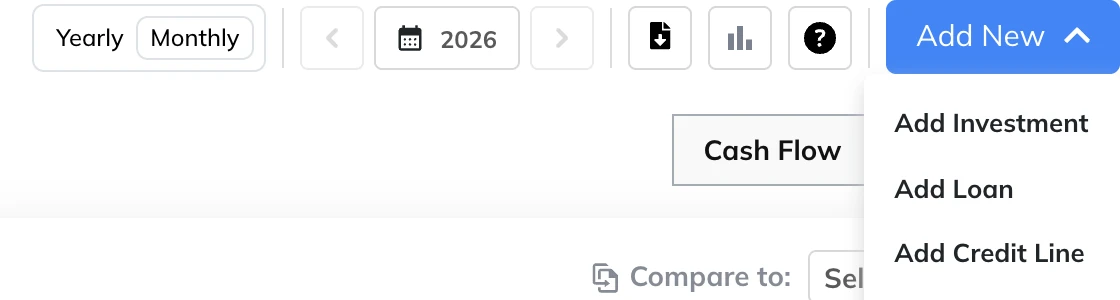
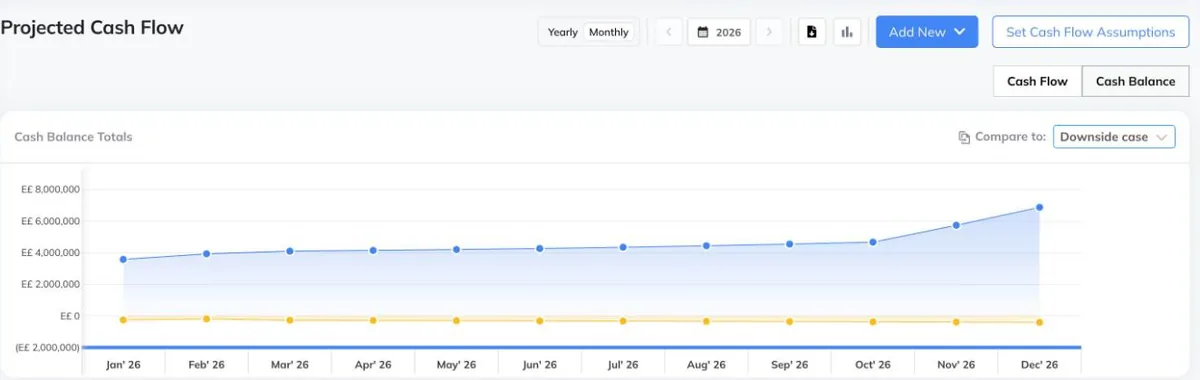
Not sure which fits? Build each option as a what-if scenario in BznsBuilder: one with a bank loan, one with an investor. Compare the cash balance, profit and repayments month by month, and choose with numbers instead of instinct. Launch includes 1 scenario, Build up to 3, Decide up to 10.
Step 4: Prepare what lenders and investors ask for
- A business plan that explains the offer, the customer and how you will sell. See how to write a business plan.
- A 3-year financial forecast: sales, profit and cash flow, with the assumptions behind them. No history yet? See how to forecast without historical data.
- A cash-flow view that shows the months when repayments are due and how much cash is left.
- The use-of-funds table from step 2.
- Registration and identity documents, and details of any collateral or guarantor a lender may ask for.
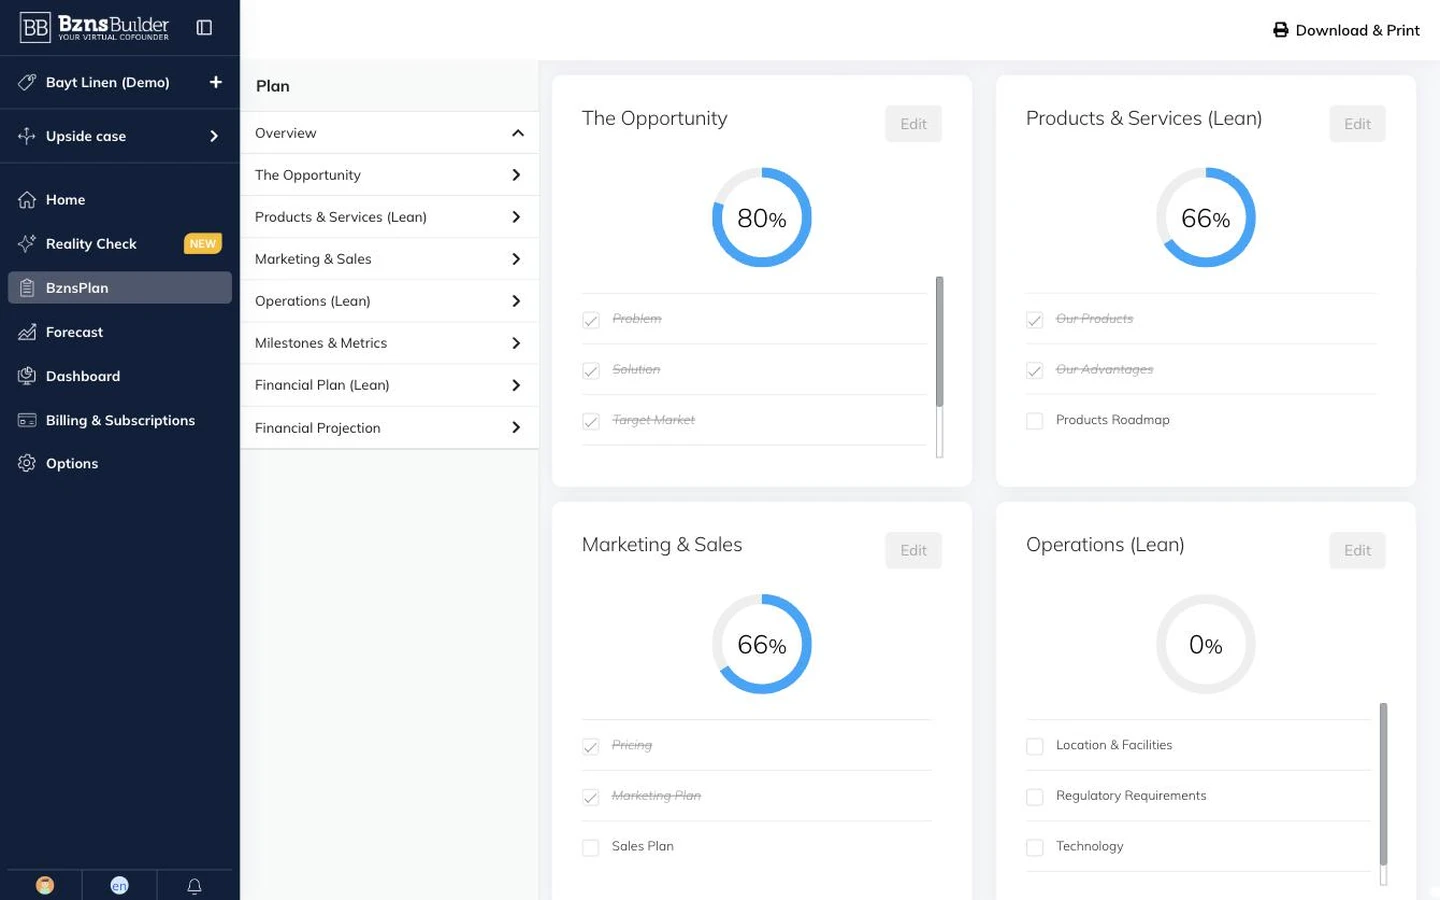
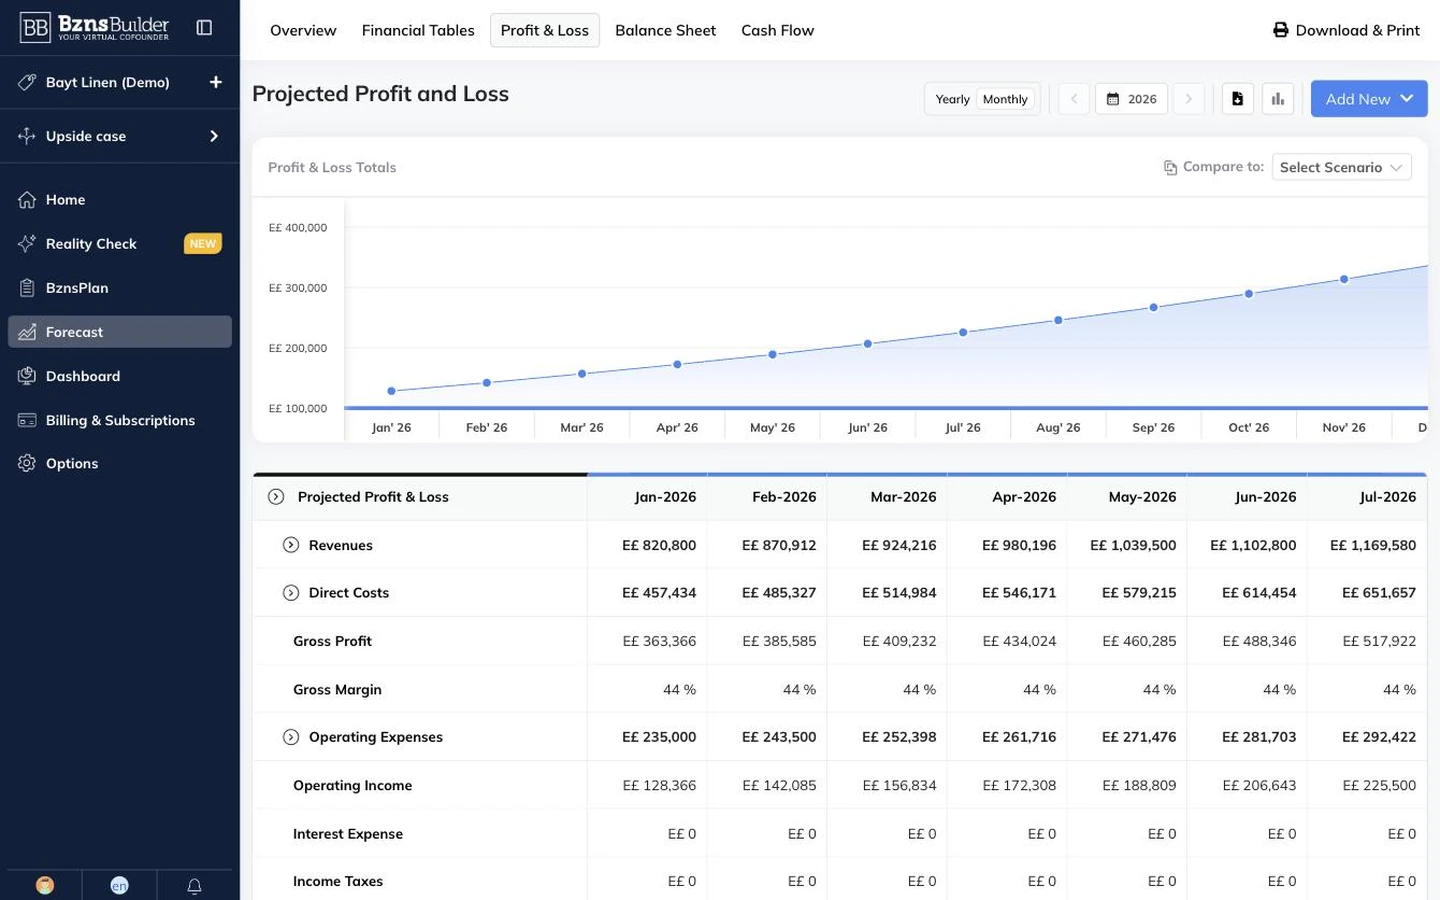
Build your whole lender pack in one place. BznsBuilder’s guided business plan takes you section by section, from the opportunity to the financial plan, and its forecast fills the financial section with the profit and loss, balance sheet and cash flow lenders expect. Download everything as PDF or Excel, or on the Build plan share a link so the bank or investor always sees your latest numbers.
Step 5: Pitch and negotiate
Open with the amount, what it pays for and when it pays back, then the evidence: early sales, signed customers or a tested price. Prepare answers to the questions every lender and investor asks: what happens if sales are 30% lower, how you will repay, and why you are the right team. A what-if scenario in BznsBuilder answers the first two with numbers: copy your forecast, cut sales by 30%, and show the lender the cash still covers the repayments. For investor pitches, see how to write an elevator pitch and pitch deck and our guide to applying to Shark Tank Egypt.
Step 6: Manage the money after you receive it
How you use the money affects your chance of getting more. Keep it simple:
- Keep the funds separate in a business account, and spend them on the lines in your use-of-funds table.
- Compare plan and actual every month. If stock sells slower or costs rise, update the forecast before the cash runs low, not after.
- Watch your cash runway, the number of months your cash will last. See how to calculate cash runway.
- Report to lenders or investors on a fixed schedule, monthly or quarterly: what you spent, what it achieved and what changed.
- Hire carefully. Add people when revenue or a clear plan supports their salaries, not just because the money has arrived.
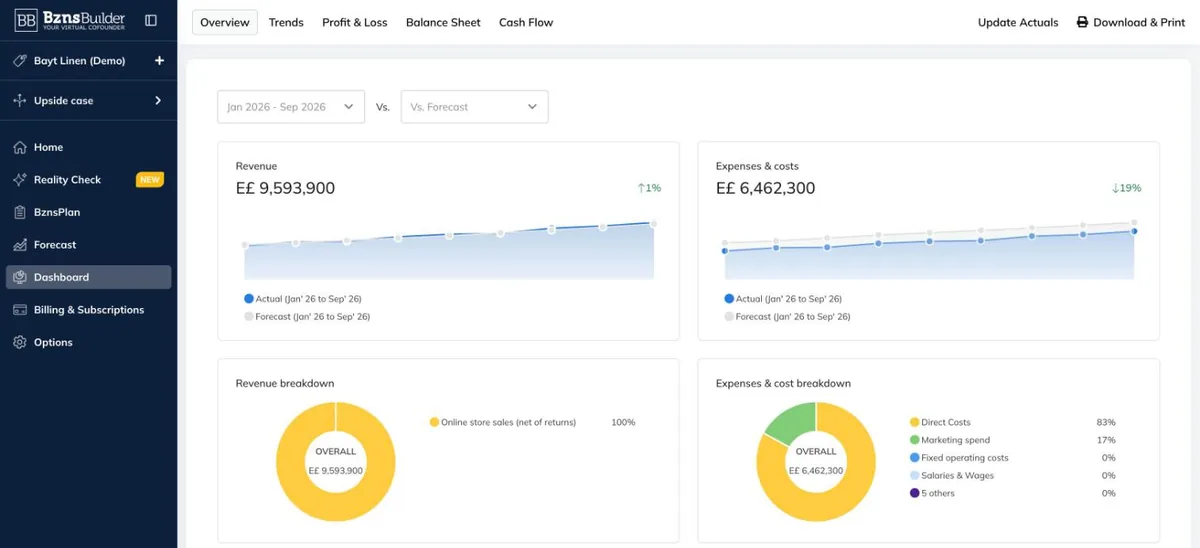
Once the money arrives, the job changes from planning to deciding. BznsBuilder’s performance dashboard compares your actual results with the plan you raised the money on, so you see where you’re ahead or behind each month. Trend analysis shows which costs and revenue lines are moving. On the Decide plan, QuickBooks integration brings in your actuals, and real-time profit and cash-flow tracking means your lender or investor update is always ready.
How BznsBuilder takes you from idea to funded
BznsBuilder covers the whole funding journey: test the idea, plan and forecast the money, then run the business on the numbers you raised it with.
| Stage | What you do | BznsBuilder features |
|---|---|---|
| Test | Check the idea justifies the money | Reality Check: six signals and a viability score out of 100 · Idea Canvas |
| Plan | Write the plan lenders read | Guided business plan, section by section, with the financial plan built in |
| Forecast | Work out the amount and prove you can repay | Financial forecast up to 10 years (P&L, balance sheet, cash flow) · Financing input for loans and investment · forecast suggestions · what-if scenarios |
| Share | Send it to the bank or investor | Unlimited PDF and Excel downloads · share via link (Build) |
| Decide | Manage the money after funding | Performance dashboard · trend analysis · real-time profit and cash-flow tracking and QuickBooks integration (Decide) |
Which plan fits where you are?
| Plan | Best for, in funding terms |
|---|---|
| Launch | Testing the idea and working out how much you need: guided plan, 10-year forecast, 1 what-if scenario |
| Build | Preparing to raise funding or apply for a loan: up to 3 scenarios, automatic forecast builder, AI-powered forecasting, monthly performance dashboard, share via link |
| Decide | After funding, when you report to lenders or investors every month: real-time dashboard, profit and cash-flow tracking, QuickBooks, up to 10 scenarios |
Every plan starts with a 7-day free trial. Compare plans.
Common mistakes when seeking funding
- Asking for a round number with no breakdown behind it.
- Forgetting the cash buffer, so the money runs out before sales arrive.
- Taking a loan whose repayments start before the business has steady cash flow.
- Giving away a large share of the business for a small amount early on.
- Applying to one lender or investor and waiting, instead of preparing several options at once.
Frequently asked questions
How much funding should I ask for?
Your startup or growth budget minus the cash you can put in yourself, rounded up to a figure you can explain line by line in a use-of-funds table. Include a cash buffer for the months before the business covers its costs.
What is the easiest funding to get for a small business?
Your own savings and family and friends are usually the fastest. For outside money, supplier credit and small loans or government-backed programmes are often easier to get than investors, especially if you have a clear plan and forecast.
Is debt or equity better for a small business?
Debt keeps you in full control but has to be repaid on schedule. Equity doesn’t need repaying but gives away part of the business. Debt suits businesses with steady cash flow; equity suits high-growth businesses that need a large amount before earning.
What documents do lenders ask for?
Usually a business plan, a financial forecast, recent bank statements or management accounts if you are already trading, registration and identity documents, and details of collateral or a guarantor. Check the exact list with each lender.
Can I get funding without a business plan?
Small amounts from family or friends, perhaps. Most banks, programmes and investors expect a plan and a forecast that show how the money will be used and repaid.
What is a use-of-funds statement?
A short table that lists what the money will pay for, how much each line costs and when it will be spent. It shows a lender or investor that the amount you ask for is planned, not guessed.
Can BznsBuilder help me prepare a funding application?
Yes. Reality Check tests whether the idea justifies the money. The guided business plan and the financial forecast (profit and loss, balance sheet and cash flow) give you what lenders and investors ask for, with the loan or investment modelled under Financing and what-if scenarios for the questions they’ll ask. After funding, the performance dashboard tracks actual results against the plan. The Build plan is designed for founders preparing to raise funding or apply for loans. BznsBuilder doesn’t apply for funding on your behalf.
Source: U.S. Small Business Administration, Fund your business. Related: break-even, startup costs.
Know exactly how much funding you need
See your cash gap before you ask.
- P&L
- Cash flow
- Balance sheet