How to Sell a Business: 9 Steps from Valuation to Closing
Short answerTo sell your business for the best price: start preparing one to two years ahead, clean up three years of accounts, value the business on adjusted profit and cash flow forecasts, reduce how much it depends on you, approach several buyers confidentially, agree terms in a letter of intent, pass due diligence, and sign the purchase agreement once you understand the tax in your country.
Key takeaways
- A sale usually takes 6 to 12 months from first approach to closing, and good preparation starts well before that.
- Buyers pay for your future cash flow, not just past profit, so your forecasts shape a large part of the price.
- Small businesses typically sell for 2 to 4 times adjusted profit. The risks you remove before the sale decide where you land in that range.
- The UK, Egypt, Saudi Arabia and the UAE tax and register a sale differently. Check the rules before you agree a price.
Disclaimer: this guide is general information, not legal or tax advice. Rules change, so speak to a qualified lawyer and accountant in your country before you act.
In this guide
- How long it takes to sell a business
- Know why you are selling
- Prepare your financials and forecasts
- Value your business (worked example)
- Business valuation calculator
- Increase your value before you sell
- Choose a broker or adviser
- Find a buyer confidentially
- From letter of intent to closing
- Tax notes: UK, Egypt, Saudi Arabia, UAE
- Plan what to do with the proceeds
- Alternatives to a full sale
- Is your business ready to sell?
- FAQ
Selling a business is as demanding as starting one. It is not just finding a buyer: you have to present the company at its best, get your financial and legal house in order, and handle the emotional side of letting go of something you built. This guide walks through each step with examples, numbers and tools to help you reach a fair price and a smooth handover.
How long it takes to sell a business
Here is the typical timeline for a small or mid-sized business sale:
| Stage | Typical duration | Main output |
|---|---|---|
| Preparation and clean-up | 6–24 months before the sale | 3 years of accounts + 3–5 year forecast |
| Valuation and pricing | 2–6 weeks | An evidence-backed price range |
| Marketing and finding buyers | 2–6 months | Teaser, NDAs and offers |
| Letter of intent and due diligence | 1–3 months | A complete data room and documented answers |
| Agreement, closing and transfer | 2–8 weeks | Signing, payment, updated official records |
1Know why you are selling
The first question any serious buyer will ask is “why are you selling?”. A clear answer builds trust and tells you what kind of deal suits you: a full sale and quick exit, a partial sale where you stay on for a transition, or a strategic partner who helps the business grow.
- Retirement or burnout: plan a handover period to pass on relationships and know-how. It reassures buyers and protects the price.
- Market timing: selling when demand in your sector is high can lift the price noticeably.
- Financial pressure: selling under pressure weakens your position. Before deciding, look at alternatives such as raising funding, and check your cash runway.
- Strategic partner: sometimes the goal is not to leave but to bring in capital or sales channels that take the business further.
- Personal reasons: entirely legitimate, and buyers appreciate honesty about them.
2Prepare your financials and forecasts
Well-organised financial records are your strongest negotiating tool. Buyers usually ask for at least three years of figures, and the clearer they are, the smaller the “risk discount” they will try to apply.
Documents to prepare
- Income statement (profit and loss) for the last 3 years, monthly if possible.
- Balance sheet (assets, liabilities and equity).
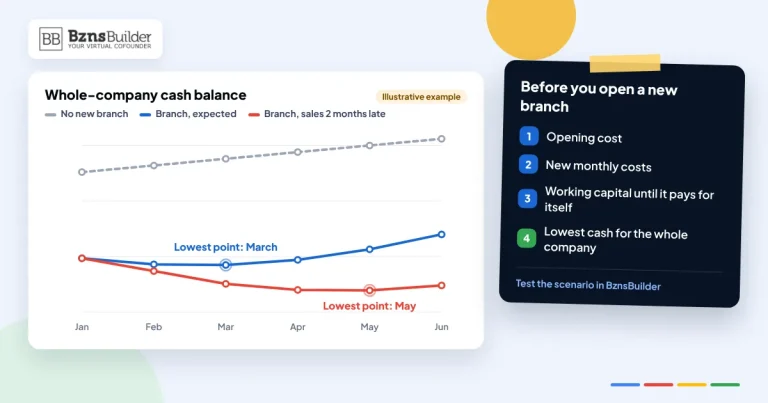
- Cash flow statement showing how cash actually comes in and goes out (see cash flow management and forecasting).
- Tax returns and proof of payment.
- Debts, loans and guarantees with their repayment terms.
- Key contracts: major customers, suppliers, leases and key employees.
Why buyers care more about forecasts than the past
A buyer pays today for profit they will earn tomorrow. Prepare financial forecasts for three to five years built on clear assumptions (sales growth, margins, costs), with a conservative and an optimistic scenario. Realistic, traceable forecasts build buyer confidence and support a discounted cash flow valuation.
If you have a business plan, update it to reflect where the business is today, or summarise your model in a one-page business plan covering revenue streams, operations, customers and competitive advantage.
Practical tip
Separate personal spending from company accounts now, and document every one-off cost. These are the items you will add back when you calculate adjusted profit, and buyers will not accept them without evidence.
3Value your business (worked example)
Valuation sets the starting point for negotiation. You can make a first estimate yourself, but for larger deals a certified valuer gives the number credibility with buyers and authorities.
Common valuation methods for small and mid-sized businesses
| Method | Best for | How it works |
|---|---|---|
| Multiple of adjusted profit | Profitable, stable businesses (most common) | Profit after adding back one-offs and excess owner pay × a multiple for the sector and risk |
| Discounted cash flow | Growing businesses or recurring contracts | Forecast cash flows for 3–5 years, discounted at a rate that reflects risk |
| Asset value | Asset-heavy or loss-making businesses | Market value of assets minus liabilities, often used as a floor price |
| Comparable deals | Sectors with available deal data | Compare with sale prices of similar businesses by size, sector and market |
Worked example: valuing on adjusted profit
Take a B2B company with net profit of $28,000 last year. The owner pays themselves $8,000 above market salary, and the company had a one-off office move costing $4,000.
| Item | Value (USD) |
|---|---|
| Reported net profit | 28,000 |
| + Owner pay above market rate | 8,000 |
| + One-off cost that will not recur | 4,000 |
| = Adjusted profit | 40,000 |
| Price range at a 2.5–3.5 multiple | 100,000 – 140,000 |
| Suggested asking price (3× multiple) | 120,000 |
Moving the multiple from 2.5 to 3.5 adds $40,000 to the price without any increase in profit. Risk makes that difference: how much the business depends on the owner, customer concentration, the quality of the accounts and the strength of the forecasts. That is the next step.
Note
Multiples vary widely by sector, country, company size and market conditions. Use the example to understand the logic, not as a fixed number for your business.
Business valuation calculator
The calculator starts with the example above. Enter your last full year’s figures to get an estimated value range using the adjusted-profit multiple method.
Your business is worth roughly $100,000 – $140,000. Buyers will ask for 3–5 year forecasts to back that number. Build them now and negotiate with clear figures.
A simplified educational estimate, not a certified valuation. Real multiples vary by sector, country, company size and market conditions.
4Increase your value before you sell
Every risk a buyer can cross off raises the multiple they will pay. Focus on these levers 6–12 months before the sale:
- Reduce dependence on you: document processes and hand key relationships to a team that can run without you.
- Diversify customers: if one customer is more than a quarter of revenue, expect a discount or extra guarantees.
- Make revenue recurring: annual contracts and subscriptions make the business more predictable and more valuable.
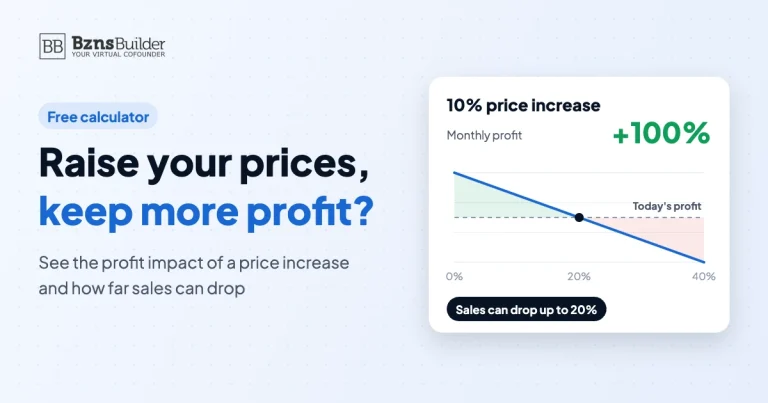
- Improve margins and cash: review your pricing and your break-even point, and cut collection days and slow stock.
- Show you can handle a crisis: buyers trust businesses with a clear crisis plan, a strategy and measurable goals.
5Choose a broker or adviser
A business broker or M&A adviser analyses the market, markets your business confidentially, screens buyers and manages negotiation and paperwork through to closing. They can be expensive, but they usually bring more offers and prevent costlier mistakes.
- When you can skip one: if the buyer is already known (a partner, employee, family member or a competitor who approached you). A lawyer and an accountant are enough.
- Avoid anyone asking for large upfront fees or promising a high valuation without evidence.
- Ask for references from past clients and deals closed in your sector and country.
6Find a buyer confidentially
Finding the right buyer can take months. Keep it confidential so staff and customers are not unsettled, and follow these practices:
- Know your buyer type: a strategic buyer (a competitor or supplier who pays more for synergies), a financial investor, or your management team.
- Prepare a short anonymous teaser, then a detailed information memorandum after an NDA is signed. Use our investor pitch guide to shape the story.
- Check the buyer can pay before you share sensitive data.
- Aim for more than one offer: competing offers are your strongest negotiating card.
- Consider seller financing (part of the price paid in instalments) to widen the pool of buyers, with clear guarantees.
7From letter of intent to closing
Once you agree in principle, the legal stage begins. Work with a qualified lawyer at every step:
| Document or stage | Purpose |
|---|---|
| Letter of intent (LOI) | Sets the price, payment structure and exclusivity period. Usually non-binding except for confidentiality and exclusivity. |
| Due diligence | The buyer reviews your accounts, contracts, assets and liabilities. A well-organised data room saves weeks. |
| Sale and purchase agreement | Price, assets or shares sold, warranties and representations, indemnities and closing conditions. |
| Non-compete and transition | The seller agrees not to compete for a set time and area, and stays on to transfer knowledge. |
| Escrow and closing | Part of the price is held until conditions are met, then documents are signed, funds move and ownership transfers. |
| Post-sale notices | Update company registers, banks and tax authorities, and inform staff, customers and suppliers. |
8Tax notes: UK, Egypt, Saudi Arabia, UAE
Rules depend on the country, the company’s legal form and who is selling, and they change over time. Review these general points with your adviser before signing a letter of intent:
- United Kingdom: individuals pay Capital Gains Tax on the gain, at 18% or 24% for shares. If you qualify for Business Asset Disposal Relief (broadly, at least 5% of a trading company you work in, held for 2 years), the rate is 18% from 6 April 2026 on up to £1 million of lifetime gains. The government has announced the lifetime limit will fall to £500,000 from 6 April 2027.
- Egypt: gains on unlisted shares are taxable: 22.5% for companies and progressive rates of up to 27.5% for individuals, while listed shares get reduced treatment. Company and shareholder records must be updated after the transfer.
- Saudi Arabia: non-Saudi, non-GCC sellers pay 20% income tax on gains from selling shares in unlisted Saudi companies, while gains on shares traded on Tadawul are exempt under conditions. Saudi and GCC owners pay zakat instead of income tax, and the articles of association and commercial registration must be updated with the Ministry of Commerce.
- UAE: if the seller is a company, the gain is subject to 9% Corporate Tax above AED 375,000 unless the participation exemption applies (at least 5% or AED 4 million cost, held 12 months). An individual selling shares as a personal investment is generally outside Corporate Tax. Procedures differ between mainland and free zones.
9Plan what to do with the proceeds
Closing is not the end of the journey. Before the money arrives, make a clear plan:
- Tax and fees: calculate them in advance, and know when they fall due if you are paid in instalments.
- Repay debts and release personal guarantees linked to the business.
- Invest and diversify with a licensed financial adviser, without rushing.
- Your next venture: if you plan a new business, start with a business plan before committing money.
Alternatives to a full sale
- Sell a stake to an investor: get liquidity while keeping part of the ownership and control.
- Merge: combine with a company whose goals and culture fit yours to grow market share.
- Transfer to family or management: preserves the legacy and shortens the search, but needs funding and a clear transition plan.
- Liquidate: the last resort when the business is not profitable. It usually returns less, but closes the business in an orderly way.
Is your business ready to sell?
Tick what applies to your business today:
Selling a business: FAQ
How long does it take to sell a small business?
Usually 6 to 12 months from first approach to closing. Start preparing one to two years before that to clean up the accounts and reduce dependence on the owner.
How do I know what my business is worth?
Small businesses are usually valued at a multiple of adjusted profit, typically 2 to 4 times, cross-checked with a discounted cash flow based on 3–5 year forecasts, and with asset value as a floor.
What documents will a buyer ask for?
Income statements, balance sheets and cash flow statements for the last 3 years, tax returns, company registration and key contracts, a list of assets and debts, and financial forecasts for the coming years.
Do I need a business broker?
Not always. If the buyer is already known, a lawyer and an accountant are enough. Selling to an outside buyer usually benefits from a broker who manages confidentiality and brings several offers, as long as they do not ask for large upfront fees.
Do I pay tax when I sell my business?
Usually yes, and it depends on the country and the seller. In the UK, individuals pay Capital Gains Tax, with Business Asset Disposal Relief at 18% from April 2026 if they qualify. In Egypt, gains on unlisted shares are taxed. In Saudi Arabia, non-Saudi, non-GCC sellers pay 20% on gains from unlisted shares. In the UAE, a selling company pays 9% Corporate Tax unless the participation exemption applies, while an individual selling a personal investment is generally out of scope. Speak to a tax adviser before signing a letter of intent.
How can I increase my business value before selling?
Separate personal spending from company accounts, reduce dependence on you and on any single large customer, move revenue to recurring contracts, and prepare realistic forecasts with scenarios that show growth continues after you leave.