How Inventory Affects Cash Flow — and How Much Stock Your Business Can Afford to Buy
Inventory affects cash flow because the cash to buy stock often leaves your business before the cash from selling that stock comes back. The longer stock sits unsold, and the longer customers take to pay, the more of your cash is tied up. To decide how much stock you can afford, forecast the lowest cash balance the order creates and compare it with the minimum cash you want to keep.
Key takeaways
- Buying stock is cash out now; it only becomes a cost in your profit and loss when the stock is sold.
- Days inventory outstanding (DIO) shows how many days your cash sits in stock before it is sold.
- Judge an order by the lowest cash point it creates, not only by its margin or its final cash balance.
- Test a smaller order, slower sales and later customer payments before you commit.
That means the decision is not only:
Will this inventory sell?
It is also:
What will this order do to my cash balance before the stock turns back into cash?
A purchase can make commercial sense and still put too much pressure on cash in the weeks or months in between.
So before placing a larger stock order, test the timing as well as the expected sales.
How inventory affects cash flow
When you pay a supplier for inventory, cash leaves the business.
The stock may then sit for a period before it is sold. Even after the sale, the timing of the cash receipt depends on how your customers pay.
Meanwhile, the rest of the business keeps moving.
Payroll, rent, suppliers, loan repayments and other operating commitments do not disappear because more money has been committed to stock.
This is why inventory can create a working-capital squeeze even when you expect to sell it profitably.
If you are already seeing sales rise while the bank balance moves the other way, the broader timing mechanism is covered in Sales Are Up. So Why Is Cash Going Down?.
Do not decide from the margin alone
Suppose you can buy stock for 60,000 and expect to sell it for considerably more.
That may be an attractive commercial opportunity.
But the expected margin still does not tell you whether your business can fund the order.
You also need to know:
- when the supplier must be paid;
- when the stock is likely to sell;
- when the resulting customer cash will actually arrive;
- what other cash commitments fall due in between; and
- how much cash you want to keep available for the rest of the business.
The affordability question is about the lowest cash point created by the decision, not only the eventual result.
A practical way to test whether you can afford more stock
1. Build the base cash forecast first
Start with the business as it stands before the proposed inventory purchase.
Forecast the cash you already expect to receive and pay over the decision period.
The point is to establish what your cash balance would look like if you did not place the additional order.
If you need to build that projection first, see Business Forecasting: Creating Your First Financial Forecast Without Historical Data.
2. Add the actual purchase timing
Do not spread the inventory cost across months simply because that makes the forecast look smoother.
Use the cash timing you genuinely expect.
If the supplier requires a deposit now and the balance later, model those dates. If the order is paid in full before delivery, model that.
The question is when money leaves the bank.
3. Add the cash expected back from the stock
Next, reflect when you realistically expect the inventory to turn into collected cash.
That may be different from the date on which you expect to record the sale.
A faster sales assumption can make a stock purchase look easier to fund. A slower assumption keeps cash tied up for longer.
That makes sales timing an assumption worth testing rather than treating as a certainty.
4. Choose the minimum cash balance your business needs
There is no universal cash buffer that works for every SME.
Choose a level based on the commitments, risks and operating needs of your own business.
Then compare that threshold with the forecast after the inventory purchase.
A useful check is:
Cash headroom = lowest projected cash balance after the decision − your chosen minimum cash balance
If that number falls below zero, the proposed plan breaches the cash buffer you chose. To see how many months that buffer would last if sales slowed, calculate your cash runway.
That does not automatically tell you to cancel the purchase. It tells you that something in the plan has to change before the decision fits the cash position you want to maintain.
5. Test more than one scenario
A single forecast gives you one set of assumptions.
An inventory decision usually deserves at least one alternative.
For example:
- What if you place the smaller order?
- What if you place the larger order?
- What if stock sells later than expected?
- What if customers pay later? (If you are being asked for longer terms, see whether to offer longer payment terms to win a bigger contract.)
- What if an existing business payment falls in the same month?
The useful comparison is not only which scenario produces the highest eventual cash balance.
Look at when cash reaches its lowest point in each scenario.
Illustrative example: two stock orders, very different cash pressure
Illustrative example only. All figures below are fictional, shown in a generic currency unit, and are not benchmarks for any country or industry.
This is a simplified monthly cash-flow example. It compares month-end balances only. It does not model the exact day on which every payment or receipt happens, so it does not show the lowest intramonth bank balance.
A business starts with 100,000 in cash.
Before the proposed stock purchase, its forecast net cash movements are:
- Month 1: +20,000
- Month 2: +10,000
- Month 3: +15,000
The founder is considering two additional inventory orders.
The business has chosen 50,000 as its own minimum month-end operating cash balance for this decision.
Scenario A — no additional inventory order
| Month 1 | Month 2 | Month 3 | |
|---|---|---|---|
| Month-end cash | 120,000 | 130,000 | 145,000 |
Scenario B — 60,000 stock order
For this simplified example, assume the 60,000 supplier payment falls in Month 1.
The additional stock then produces 30,000 of collected cash in Month 2 and 50,000 in Month 3.
| Month 1 | Month 2 | Month 3 | |
|---|---|---|---|
| Month-end cash | 60,000 | 100,000 | 165,000 |
The lowest month-end cash balance shown is 60,000.
Against the business’s chosen 50,000 month-end minimum, the lowest headroom shown is:
60,000 − 50,000 = 10,000
Scenario C — 90,000 stock order
Now assume the business places the larger 90,000 order in Month 1.
The additional stock produces 40,000 of collected cash in Month 2 and 70,000 in Month 3.
| Month 1 | Month 2 | Month 3 | |
|---|---|---|---|
| Month-end cash | 30,000 | 80,000 | 165,000 |
The lowest month-end cash balance shown is 30,000.
Against the same 50,000 month-end minimum:
30,000 − 50,000 = −20,000
Both inventory scenarios finish Month 3 at 165,000 because, in this deliberately simplified example, each order produces the same 20,000 net incremental cash over the three-month period:
- 60,000 order: 80,000 collected − 60,000 paid = 20,000
- 90,000 order: 110,000 collected − 90,000 paid = 20,000
What changes is when the cash leaves and comes back.
The larger order requires an extra 30,000 of cash in Month 1. That extra 30,000 does not return until later in the example. So Scenario C creates more interim cash pressure even though both scenarios reach the same Month 3 balance.
That is the decision the ending balance hides.
And because these are monthly balances, the example makes one further limitation explicit: the business’s actual bank balance could fall below the reported month-end figure during a month if payments occur before receipts.
The example therefore does not prove that the 60,000 order is safe or that the 90,000 order is unaffordable. It shows how a founder can compare the cash path created by different assumptions before deciding what level of pressure is acceptable.
How long does inventory tie up your cash? Days inventory outstanding and the cash conversion cycle
Two standard measures show how long cash stays locked in stock.
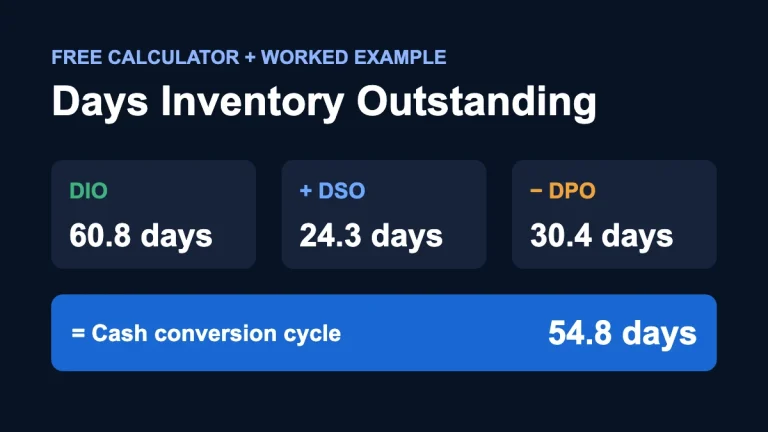
Days inventory outstanding (DIO) is the average number of days stock is held before it is sold:
DIO = (Average inventory ÷ Cost of goods sold) × Number of days in the period
This is the same formula the Corporate Finance Institute uses. A related measure, inventory turnover, is cost of goods sold ÷ average inventory: how many times you sell through your stock in the period.
Illustrative example: a business holds 90,000 of stock on average and has 540,000 of cost of goods sold over a year. Its inventory turnover is 540,000 ÷ 90,000 = 6 times a year, and its DIO is (90,000 ÷ 540,000) × 365 ≈ 61 days. On average, cash spent on stock takes about two months to come back as a sale.
The cash conversion cycle adds the customer and supplier side:
Cash conversion cycle = DIO + Days sales outstanding − Days payables outstanding
If the same business collects from customers in 45 days and pays suppliers in 30, its cycle is 61 + 45 − 30 = 76 days. That is roughly how long each pound, riyal or dollar spent on stock is away from the bank. A bigger stock order, slower sales or longer customer terms all lengthen the cycle and increase the cash you need.
Use these measures to spot a trend in your own business over time. There is no single good DIO for every SME: it depends on your industry, product shelf life and supplier lead times.
Need the full picture? Use the DIO, inventory turnover and cash conversion cycle calculator, which also adds the days customers take to pay and the days you take to pay suppliers.
Where open-to-buy fits
Retailers often use open-to-buy, or OTB, to control merchandise purchasing.
OTB uses planned sales and inventory targets to establish how much additional stock can be bought during a planning period. For retailers with a large number of products or regular buying cycles, it can be a useful purchasing discipline.
But it answers a narrower question than the full cash forecast.
An OTB budget focuses on merchandise.
Your business cash forecast also has to account for everything else competing for the same cash.
So a retailer can use both views:
What does the merchandise plan say I should buy?
and
What happens to the whole business’s cash if I buy it now?
Those are related questions. They are not identical.
Warning signs that the order deserves another scenario
Test the inventory purchase again if:
- the order materially reduces your available cash;
- sales timing is uncertain;
- a large share of the expected cash arrives well after the supplier is paid;
- the decision depends on one unusually strong sales assumption;
- the business has other major payments due during the same period; or
- a larger order looks attractive mainly because of the eventual margin rather than the cash path.
The objective is not to forecast perfectly.
It is to find the assumptions that could change the decision before the cash is committed.
How to test the decision in BznsBuilder
See how scenario comparison works in BznsBuilder →
The first job is to build a financial forecast that reflects the assumptions you actually want to test.
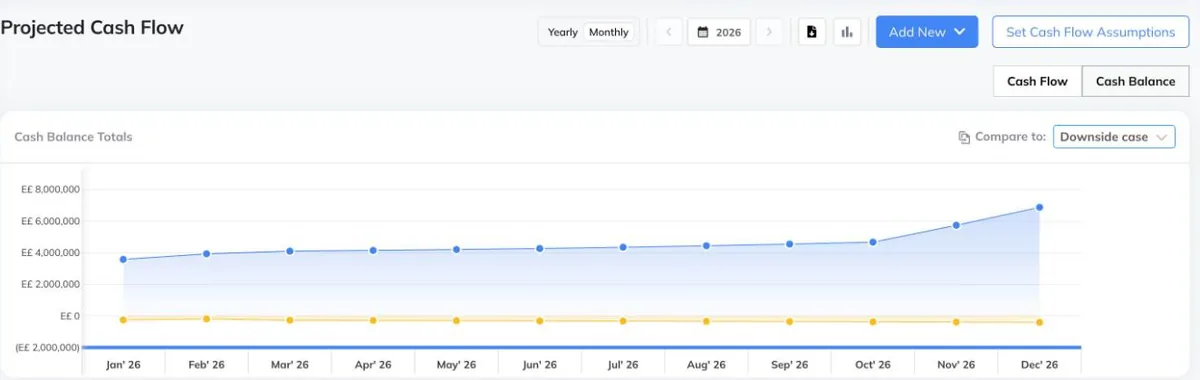
BznsBuilder generates financial forecasts covering profit and loss, balance sheet and cash flow, and lets you compare alternative assumptions through what-if scenarios.
For an inventory decision, use the forecast to represent the expected financial effect of your current plan, then compare it with an alternative scenario—for example, a different purchasing or sales assumption—and examine what happens to forecast cash.
The exact way an individual inventory purchase is represented will depend on how that business’s forecast is structured. This article does not assume a dedicated inventory-purchasing module or transaction-level stock workflow.
The useful comparison is the financial result: how does the alternative assumption change the forecast cash position?
You can read more about BznsBuilder’s financial forecasts and scenarios.
Before you commit to the stock order, compare your base forecast with an alternative scenario and check what changes in forecast cash. Start your 7-day free trial.
The decision is about the cash path, not only the stock
Inventory can be an asset to the business and still absorb cash at an awkward time.
So do not ask only how much stock you want, how much you can sell or what margin the order could make.
Ask:
After I pay for this inventory, what is the lowest cash balance my business reaches before that money comes back — and am I prepared to operate through it?
That turns an inventory purchase from a buying decision into a financial decision.
For the wider numbers that need to stay connected around decisions like this, see Managing Small Business Finances: How to Manage Them Effectively. To check how much you need to sell to cover your costs, including the stock you carry, use our break-even point calculator, and lay the order out month by month in a 12-month cash flow forecast.
Related guides: plan the next year month by month with the free 12-month cash flow forecast template, find your cash low point with the free tool in our cash flow management guide, see how many months your cash will last with the cash runway calculator, and work out the sales you need to cover your costs with the break-even guide.
Frequently asked questions
Does buying inventory reduce cash flow?
Yes. Paying a supplier for stock is cash out of the business when you pay. The cash comes back only when the stock is sold and the customer pays, so a larger order lowers your cash balance in between.
Is inventory an expense?
Not when you buy it. Unsold stock is an asset on the balance sheet. It becomes an expense, cost of goods sold, in your profit and loss when the stock is sold, which is why profit and cash can tell different stories.
How does an increase in inventory affect the cash flow statement?
An increase in inventory reduces operating cash flow, because cash has gone into stock that has not yet been sold. A decrease in inventory adds to operating cash flow.
Inventory turnover vs days inventory outstanding: what is the difference?
They measure the same thing from two sides. Inventory turnover is how many times you sell through your stock in a year (cost of goods sold ÷ average inventory). Days inventory outstanding turns that into days (365 ÷ turnover), which is easier to compare with your supplier payment terms.
What is a good days inventory outstanding?
It depends on your industry, shelf life and supplier lead times, so there is no single target. Track your own DIO over time: a rising figure means cash is sitting in stock for longer.
How much inventory can my business afford to buy?
Forecast your cash with and without the order, find the lowest balance the order creates, and compare it with the minimum cash you want to keep. If the lowest balance falls below that minimum, change the order size, timing or payment terms before you buy.
See how much stock your cash can carry
Test purchases against your monthly cash.
- P&L
- Cash flow
- Scenarios